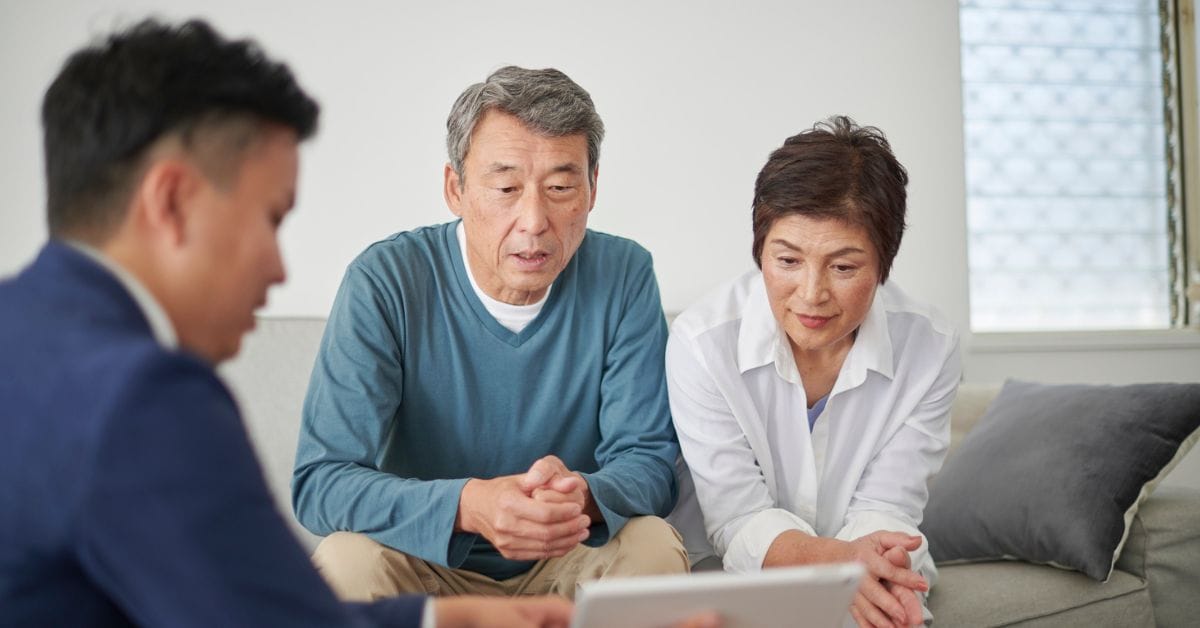
Choosing the right financial advisor Singapore can feel overwhelming, especially with so many titles, firms, and fee structures in the market. Whether you want to start your first savings plan, build a retirement portfolio, or protect your family with insurance, the right advisor can help you make informed, responsible, and long-term financial decisions.
In this article, we break down the types of financial advisors in Singapore, what to ask before you engage one, how MAS regulates the industry, and a simple checklist to help you choose confidently.
Learn more: Health Insurance & Panel Doctor Networks
Schedule a consultation with a Licensed Financial Advisor for general guidance
Why Working With a Financial Advisor Matters in Singapore
Singaporeans deal with unique financial responsibilities: high living costs, healthcare expenses, home ownership planning, and long-term retirement needs under CPF. A qualified financial advisor helps you navigate these complexities and make decisions that suit your life stage, goals, and risk profile.
A good advisor should:
- Understand your needs and goals thoroughly.
- Recommend suitable and not excessive financial products.
- Provide clear explanations of benefits, limitations, and risks.
- Practise full transparency on fees and commissions.
- Maintain ongoing reviews so your plan stays relevant.
Types of Financial Advisors in Singapore
Financial advisors in Singapore generally fall into three main categories. Understanding the difference helps you know the scope of advice you can receive.
1. Tied Agents (Representatives of a Single Insurer)
These advisors represent one insurance company only. They can offer the insurer’s full suite of products such as life insurance, critical illness plans, retirement annuities, investment-linked policies (ILPs), and savings plans.
Pros
- Strong product knowledge of a single insurer.
- Good for clients who already prefer a specific brand.
Cons
- Recommendations are limited to one insurer’s offerings.
- Less flexibility when comparing cross-insurer solutions.
2. Financial Advisory (FA) Representatives
FA firms are licensed to carry products from multiple insurers and investment providers. Advisors under FA companies can compare across insurers.
Pros
- Access to a wider range of products and price points.
- More flexibility in fitting solutions to individual needs.
Cons
- Product choice still depends on the insurers and providers approved by the FA firm.
3. Independent Financial Advisors (IFAs)
Independent advisors are not tied to any insurer. They typically offer the broadest range of solutions and are compensated mainly through fees, not product commissions.
Pros
- Wide product access.
- Often more transparent, fee-based advisory models.
Cons
- Advisory fees may be higher.
- Not all clients require full independent planning.
Questions to Ask Before Choosing Your Financial Advisor
Before engaging any advisor, ask these essential questions. The answers will show you the advisor’s professionalism, ethics, and suitability.
1. Are you licensed by MAS and which company are you representing?
Every advisor must be licensed under the Monetary Authority of Singapore (MAS). You can verify this through the MAS Financial Institutions Directory or Representative Search Tool.
2. What types of products are you able to advise on?
Ensure the advisor can recommend solutions appropriate for your goals. Some may specialise in insurance only, while others can advise on investments, wealth accumulation, retirement, or legacy planning.
3. How are you compensated?
Ask whether the advisor earns:
- Commissions.
- Advisory fees.
- A combination of both.
This helps you understand any potential conflicts of interest.
4. What is your review and servicing process?
Ongoing reviews are essential, especially for long-term financial plans. Ask how often they will meet you and what support you can expect after policy issuance.
5. What is your experience with clients who have needs similar to mine?
An advisor experienced with your demographic (e.g., young families, early career professionals, retirees, self-employed individuals) will likely provide more relevant guidance.
How MAS Regulates Financial Advisors in Singapore
MAS has strict regulations to protect consumers and ensure responsible advice. Some key regulatory frameworks include:
1. Representative Licensing
All financial advisors must be appointed and listed in the MAS Register.
2. Needs-Based Advisory
Advisors must conduct a full fact-finding process to understand your:
- Financial goals.
- Risk tolerance.
- Budget.
- Existing policies.
Recommending products without this process violates MAS guidelines.
3. Product Suitability Requirements
Any product recommended must be suitable for the client. Advisors must explain:
- Benefits.
- Limitations.
- Fees and charges.
- Risks.
4. Disclosure of Remuneration
MAS requires clear disclosure of commissions or fees earned.
5. Compliance and Training
Advisors must attend continuing education to keep their licence active.
Checklist for Choosing the Right Financial Advisor in Singapore
Use this simple checklist to evaluate any advisor you meet:
✔ Confirm MAS licensing.
✔ Check company representation (tied, FA firm, or independent).
✔ Ensure a proper financial needs analysis is done.
✔ Ask about product range and limitations.
✔ Request clear explanations of fees and commissions.
✔ Assess how transparent and patient the advisor is.
✔ Check whether recommendations match your goals.
✔ Understand their review cycle and after-sales servicing.
✔ Look at client testimonials, if available.
✔ Choose someone who makes you feel comfortable and never pressured.
Find A Financial Adviser

[SG] Featured Doctor
Featured Story
Connect with a Licensed Representative
Looking for professional advice? Contact us for an introduction to a licensed financial adviser to help with your inquiries.
Disclaimer: 365Asia is an introducer and may receive compensation for this introduction. We are not licensed financial advisers and do not provide financial advice
Frequently Asked Questions (FAQs)
How much does it cost to engage a financial advisor in Singapore?
Most advisors do not charge upfront consultation fees. Their compensation usually comes from product commissions. Some independent advisors may use fee-based models. Always ask for full transparency before engaging.
How do I verify whether a financial advisor is licensed?
You can search the advisor’s name using the MAS Representative Search Tool. This confirms their accreditation and the scope of products they can advise on.
What is the difference between a tied agent and an FA representative?
A tied agent represents one insurer only, while an FA representative can recommend products from multiple insurers approved by the FA firm. Both must follow MAS regulations.
What should I prepare before meeting a financial advisor?
Bring details of your income, existing insurance policies, investment holdings, debts, and financial goals. This helps the advisor perform a proper needs analysis.
Can I change my financial advisor later?
Yes. You can switch servicing agents or work with a new advisor if your current one is unresponsive or does not meet your expectations. Policies remain valid as long as premiums are paid.
Disclaimer: This page is for general information only and does not constitute financial advice. Please consult a licensed financial consultant for personalised advice. Consultants featured on 365Asia are licensed and partners of our platform.